About Sell Odds.
Sell Odds is a valuation and probability engine developed by Gregory Alan Anderson, REALTOR®, California DRE# 01071792, proudly representing KW Executive, DRE# 02003950. Sell Odds runs on empirical California Regional Multiple Listing Service (CRMLS) data across its whole footprint: closed sales for the value, sold-and-unsold outcomes for the odds. For a subject property, the engine returns an estimated value, where it can give one, with a likely range and an estimate strength, and a sale probability at each list price it can score, given the local outcome record. Greg’s in-person assessment of condition and authenticity is separate from the engine’s value and probability estimates. His advice on pricing or an offer draws on both. The proprietary formula stays private. The published methodology and the disclosures on this page govern how Sell Odds output appears throughout this site.
CRMLS data source. Sell Odds is built and operated by Greg Anderson as a CRMLS subscriber under the CRMLS Data License Agreement. The figures published on this site are aggregated, derived counts from the CRMLS record, such as how many listings in a city sold or failed and how long they took. This site does not redistribute hyperlocal CRMLS data, including expired, withdrawn, off-market, or address-level outcome detail. Reader access to listing-level unsold detail flows through a client login under CRMLS VOW rules on the Arroyo Casa property pages, and in person.
Style and architect curation. CRMLS does not enforce an architectural-style field, and agent remarks are inconsistent on style attribution. Where a page on this site discusses a style or an architect, the reading is Greg Anderson’s, made against hand-identified properties, not a statistic cut from the MLS. Sell Odds does not judge whether a style is genuine or who designed a house.
Not an appraisal. Sell Odds is not an appraisal, not a guarantee of sale price, sale timing, or marketability, and not investment, legal, or tax advice. Past outcomes do not guarantee future results. Property-specific factors, market conditions, timing, presentation, and other variables outside the model’s scope can move actual outcomes materially. Where Sell Odds output informs a list-price or offer-price recommendation for a specific property in the course of brokerage services, the recommendation is an opinion of value given by a California real estate licensee in the ordinary course of business, identifies its market-data basis, names this site’s methodology as the published basis, and is not an appraisal under California Business and Professions Code §11302(b).
A listing that fails to sell is evidence to investigate, not proof of one cause. Price is one part of that investigation, alongside condition, presentation, documentation and timing. I built Sell Odds so the price is never set blind.
Six guides on Sell Odds put this method to work on particular questions. A Pasadena seller can start with choosing a listing agent for a Pasadena character home and pricing a character home in Pasadena. Anywhere else, how to choose an agent for a historic or character home sets out what to ask. For the odds at a given price, read the odds a home sells at a given price; for what makes an architectural home worth more or less, read what an architectural home is actually worth. Buyers can start with finding a character home in the San Gabriel Valley.
Why is the San Gabriel Valley hard to price?
Because it is not one market, and little in it behaves the way a portal’s estimate says it should. Pasadena, South Pasadena, Altadena, Sierra Madre, San Marino, Alhambra: none of these is one market. A Craftsman in Bungalow Heaven and a Craftsman in Altadena share an architectural style and almost nothing else. A historic-district designation moves the price in one direction. The Mills Act moves it in another. Lot configuration, school boundary, foothill aspect: each one is a number that moves the price, and none of them is what a guesstimate sees.
What question does Sell Odds actually answer?
Two, and they are different numbers. Sell Odds is a valuation and probability engine: it estimates what the house is worth, and it estimates the probability that this property will actually sell at this price. Worth is one number. Whether a property will sell at a given price, estimated from the record of what this market has already done, is a different number entirely, and it is the one that decides whether you move or you sit. Sell Odds answers both, and this page is the record of how.
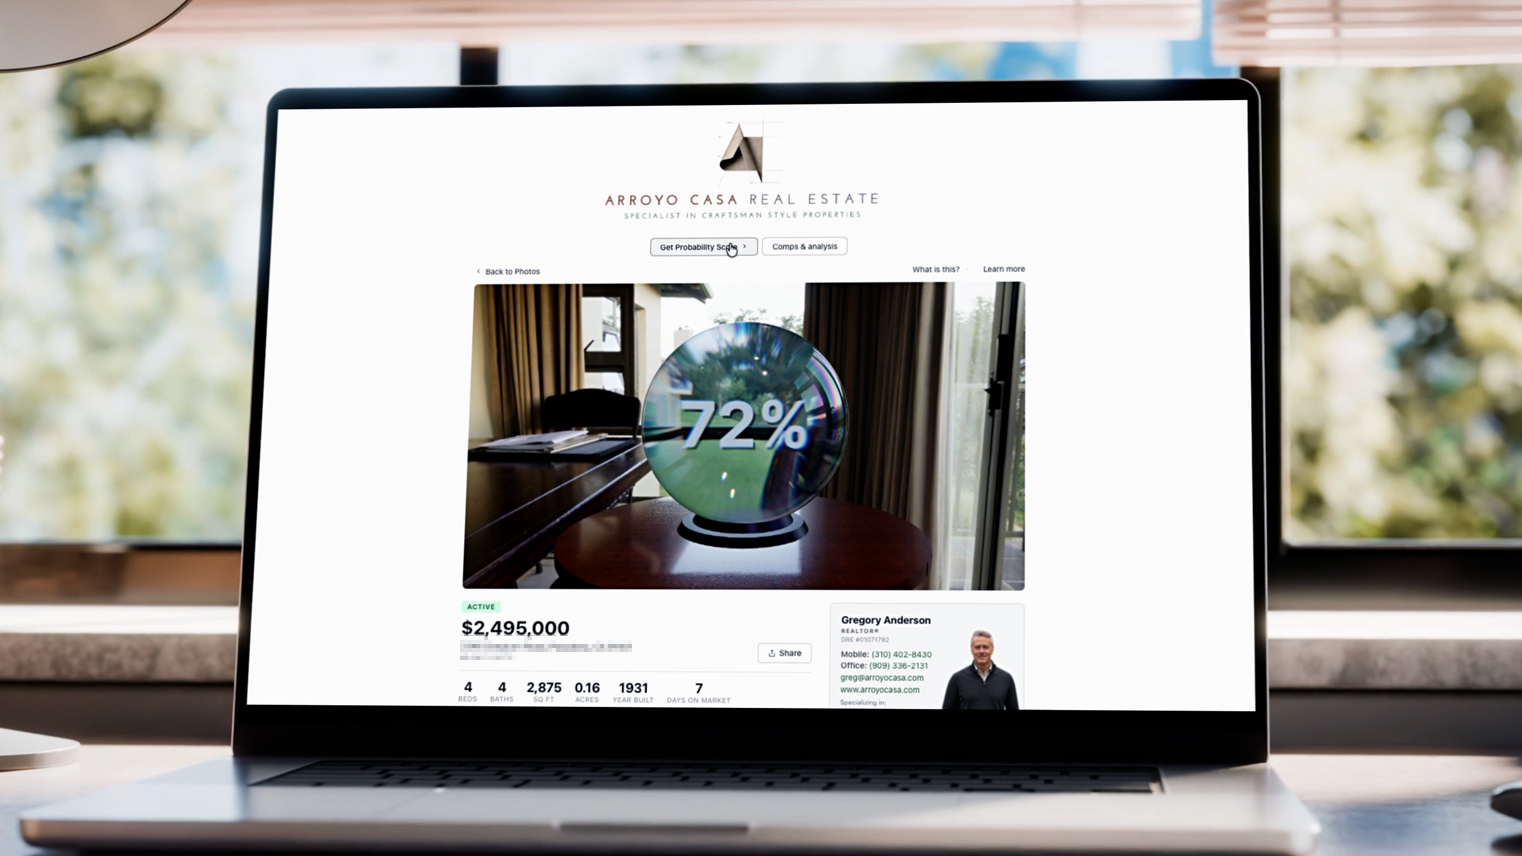
Sell Odds began as its own product, separate from any single market. Its proving ground and full development story live at sellodds.com. What runs on Arroyo Casa is the same engine that runs across the entire CRMLS, with no thumb on the scale for any city. Same math. Same data discipline. To see it work, find any property in the Arroyo Casa search, click Get Sell Odds Probability Score, and watch the Crystal Ball run Sell Odds against that property, at that moment. The number it returns is an estimate built from the market’s record. The engine answers those two questions; the questions that surround them, when to list, what to prepare, what the city requires before escrow can close, are gathered in the Seller FAQ: Historic and Architectural Homes in Pasadena and the San Gabriel Valley.
Where does the math behind Sell Odds come from?
It comes from the discipline finance has used for sixty years. In the early 1960s, a mathematics professor named Edward Thorp published Beat the Dealer and proved the blackjack table could be beaten with probability math. Then he took the same math to Wall Street. The fund he co-founded in 1969, Princeton Newport Partners, is widely regarded as the first quantitative hedge fund, and its record still reads like a misprint: nineteen winning years in nineteen. Empirical math built modern quantitative finance on that foundation. It is how serious money has measured probability ever since: not by opinion, but by the record of outcomes. The valuation architecture was informed by the published technical overview of the Quantarium Residential Valuation Model.
Why has residential real estate not used this math?
It never adopted it. Six decades later, walk into any residential transaction and look for that math. It is not there. What consumers get instead is the Zestimate. Zillow, Redfin, homes.com, all the portals people doomscroll in bed at half past midnight: every one of them is a lead-generation business, and the estimate is the bait. Your contact information is the product. Those platforms want the listing. They are not built to help you make a better-informed decision, and the number on the screen is an estimate of worth, not the probability your property will sell at it.
An investment-grade discipline for measuring probability sat in plain sight for sixty years while the industry handling the largest transaction of most families’ lives ignored it. I couldn’t watch it anymore. So I designed what did not exist.
What data does Sell Odds run on?
Sell Odds is built on the California Regional Multiple Listing Service. The value is built from closed sales; the odds are built from sold and unsold outcomes. The source records come from the CRMLS, not from scraping consumer real estate websites. Sell Odds uses those records to generate its value and probability estimates. The property’s own record is read live the moment you open it, and every score is calculated fresh, for the property in question, at the moment it is requested. The valuation models are rebuilt every week from the newest closings and tested against the last 90 days of sales across the CRMLS.
Why are active and pending listings excluded?
Because neither one proves anything about market acceptance. The odds use sold and unsold outcomes only. Active listings are excluded, because a price sitting on the market proves nothing about market acceptance. Pending listings are excluded, because they have not closed. What remains is the empirical record of what the market did: the properties that closed, and the properties that came to market, sat, and walked away unsold.
Here is the part that matters. Every licensed agent in California can open the MLS and look at that failure record, one listing at a time. Few of them can do anything with it. Nothing in an agent’s toolkit aggregates tens of thousands of outcomes and turns them into a probability, and no human reads that many outcomes off a screen. Software has to do it. The software did not exist. So I built it. That is the whole point.
How is a Sell Odds read different from a CMA?
It is held to a different standard of evidence. The value starts where an appraiser starts, with the closest sales, each adjusted for market movement, for differences such as size, rooms, age, lot, garage, pool and view, and for location. The odds come from empirical math, the same discipline finance runs on. What the value takes from appraisal is a sales-comparison discipline, held to defined, auditable comparable-sale rules. Licensed appraisers are trained, tested, and bound to strict, recognized approaches to value: the sales comparison approach, the cost and replacement approach, the income approach, and the disciplined variants built on them. The approach changes with the property. The discipline never does: defined criteria, defensible adjustments, a conclusion that can be audited.
Real estate agents carry no such requirement. Nothing in an agent’s licensing educates them in a valuation discipline, and nothing obligates them to acquire one. So what most sellers receive as a CMA, a Comparative Market Analysis assembled at the kitchen table on the day an agent is trying to win the listing, is photographs of nearby homes with similar bedroom counts, presented as analysis.
And there is a harder truth about that kitchen-table package. The comps in it are routinely cherry-picked to flatter the number, because the agent’s goal that day is your signature, not your outcome. The industry has a name for this. It is called buying the listing. It is one of the oldest open secrets in the business, it has run for decades, and the overpricing born at that table is where many failed listings begin.
A conventional market analysis and a Sell Odds read provide complementary evidence. The Probabilistic Marketing Analysis shows how the estimated probability of sale changes with the asking price. Empirical math, held to defined, auditable comparable-sale rules, applied at a scale no individual can work at. On any Arroyo Casa property, How the value and the Sell Odds score were worked out shows the sold comparables the engine chose for it, mapped around the home. Each one is adjusted to the subject line by line: market movement since the sale, living area, lot, year built, bedrooms, bathrooms, garage, pool, view and location. You see every comp’s weight and its distance from the home. Sold data, auditable rules, on demand, free.
Eight Filtering Gates. Zero Exceptions.
Every score runs through eight gates before the engine produces a single probability.
Adaptive tiered radius. The comparable search starts half a mile around the property and widens only when the data requires it. A hard ten-mile ceiling limits cross-submarket contamination, and nearer homes count more.
Structural matching. Bedrooms and bathrooms within one, living area within 30%. Gated, not suggested. A four-bedroom home is never compared to a two-bedroom.
Three-year rolling window. Old enough to capture three full seasonal cycles. Recent enough to reflect current conditions.
Price banding. Asking prices more than double or less than half what comparables sold for are excluded before they can distort the estimate.
Sold and failed outcomes. The engine reads what sold and what did not: expired, withdrawn, canceled. Both sides of the record, always.
Minimum thresholds. If the data is not sufficient for a reliable estimate, the system says so. It does not fabricate confidence.
Lease contamination filtering. Rental listings and distressed sales (short sales, bank-owned homes, auctions) are detected and excluded. A rental comp is not a sale comp.
Property subtype matching. Single-family to single-family. Condominiums to condominiums. Manufactured to manufactured. No blending.
Is the Sell Odds number a prediction or a measurement?
A tested prediction, built on recorded outcomes. The probability Sell Odds returns is its estimate of the chance that a listing with this as its last asking price ends in a closed sale. Exactly what goes into it: each comparable listing once, at the last asking price it carried, as sold if it closed and as unsold if it expired or was withdrawn or canceled. A sale counts however long the home took to sell. Price changes inside a listing are not read, so a listing that cut its price and then sold counts as a sale at its final asking price, and never as a failure at the price it started at. A listing taken off the market and put straight back at the same price is the same offer continuing, not an unsold listing. An unsold listing records only that the listing ended without a sale; it does not prove the home could never have sold at that price. The estimate comes from where this price sits against what comparable homes were asking when they closed and when they did not, and from how often homes like this one sell nearby. It is tested on listings it has never seen, and if it cannot beat a simple local average, it does not print. A high number means the market has a strong track record of closing at that level. A low number means properties in that range have a history of expiring or being pulled.
There is no black box behind the number. Every property page shows its work under How the value and the Sell Odds score were worked out: the comparable homes, the rules each one had to pass, the weight each one carried, and how the score has held up on listings it never saw. The Crystal Ball does not tell you what to do. It shows you the odds, built from what the market has done.
What does moving the price slider show?
It shows the shape of the curve, which is where the leverage lives. A single probability at a single price is useful. Move the price slider on any property and the Crystal Ball shows the probability at every price it can score, from the low end of the value’s range to the high end, and further out when the list price sits outside that range, so you can see exactly where the probability of sale begins to drop, and how sharply. Most consumers have never seen what happens to a property’s odds when it is overpriced by $10,000 or $20,000. Now they can.
What can the Sell Odds engine not see?
Condition as it really is, and I will not pretend it can. A home two doors from yours sold last spring after a $140,000 renovation. Yours has the original kitchen. The MLS has no required field for that. Renovation detail lives, when it lives anywhere, in optional fields and free-text public remarks, and agents are notoriously inconsistent with both. I spent months trying to build a feature matrix that could reliably read remodels, additions, and ADUs out of public remarks. The remarks are too inconsistent. What the engine does now is narrower: for a home with a current listing, its final adjustment reads the listing’s own condition field, where an agent filled it in, and the words of its description with every price and number removed, and corrects for what that record has tended to mean. It cannot see a renovation the record does not describe, and it does not judge condition. Rather than let the engine guess past its evidence, I held it to the same standard as everything else on this page: it does not fabricate confidence.
I built and remodeled homes for twenty years. I assess the house in person, including its condition, originality and work that may need specialist investigation. That assessment informs my pricing or offer advice alongside the engine’s value and probability estimates. The engine estimates value and the probability of a sale from the record; I assess the house. What I am reading when I do it is set out in Owning the Architectural Home and in Buying an Architectural Home.
Why is the public market reading citywide only?
Because the readings right around one address open through a client login under CRMLS VOW rules, not on a public page. The probability the public Crystal Ball shows is the property’s own, built from the comparable homes around it. The city view of the Market Friction Index runs beside it: sell-through rate, list-to-sale ratio, days on market and price elasticity, driver by driver, showing who holds the advantage at the table. All of it runs free, on any property, on demand.
The hyperlocal layer is a different instrument. The same readings for homes of the same kind within a mile of the address, reaching out to two miles, counting only homes close in size, when a mile is too thin. The comparable homes near yours that came off the market without selling. And the failure record itself: expired, withdrawn, and canceled listing detail is governed under IDX and VOW regulations and cannot be displayed to the general public on any website, this one included. Every licensed agent has access to that record. Few can turn it into a probability.
That layer opens through a client login, and I deliver it at your table. When I do, the record is on the screen: the unsold addresses, the failed listings, for your property at the center of the conversation. That is the quality of proof I bring.
So if you ran your property through the Crystal Ball and the number came back lower than you expected, do not price off that number alone, and do not dismiss it either. It is an estimate from the record for that price, without the house in front of it. The delta between the city reading and the hyperlocal one can be significant, and that delta is the entire conversation. Reach out and we will run it together: request your Sell Odds read and in-home analysis.
Is Sell Odds an appraisal?
No. Sell Odds is not an appraisal, not a guarantee of sale price, sale timing, or marketability, and not investment, legal, or tax advice, as the disclosure at the top of this page sets out in full. Past outcomes do not guarantee future results, and property-specific factors, market conditions, timing, presentation, and other variables outside the model’s scope can move actual outcomes materially.
Where Sell Odds output informs a list-price or offer-price recommendation for a specific property in the course of brokerage services, that recommendation is an opinion of value given by a California real estate licensee in the ordinary course of business. It identifies its market-data basis, it names this page as the published basis, and it is not an appraisal under California Business and Professions Code §11302(b).
I am Greg Anderson, REALTOR®, licensed in California since 1990, and Arroyo Casa is my practice across the architectural and character homes of the San Gabriel Valley. The engine is one instrument in that work and it is published here so you can inspect it. What it estimates and what I assess are two different things, and you are entitled to both before you set a number. When you want them together on your own property, Selling an Architectural Home is where that conversation starts.